On this page
Car Insurance in Lenexa, KS When You Rely on Your Vehicle for Work
If your daily routine depends on a working car, reviewing deductibles and transportation coverage can help you understand which expenses remain yours after a covered loss. This page covers three specific choices Lenexa households face: setting collision and comprehensive deductibles, understanding how parked-car losses are categorized, and deciding whether optional rental reimbursement belongs on your policy.
KansasAutoInsurance.com is operated by Drivers Insurance Agency Inc. Call 844-712-1313 to discuss any of the topics below. A quote does not bind coverage; ask the insurer or authorized agent to confirm when coverage takes effect and what payment is required.
What Lenexa, KS Car Insurance Must Include by Law
Kansas is a no-fault insurance state, which means your own policy pays certain medical expenses after an accident regardless of who caused it. Minimum liability alone is not all that’s required. Kansas law mandates three categories of coverage:
-
Liability: Kansas requires $25,000 bodily injury liability per person, $50,000 per accident, and $25,000 in property damage liability (25/50/25).
-
Personal Injury Protection (PIP): at least $4,500 per person for medical expenses, plus separate required disability/loss-of-income, in-home services, rehabilitation, funeral and survivor benefits. Personal Injury Protection covers medical expenses after an accident under these no-fault rules.
-
Uninsured/Underinsured Motorist (UM/UIM): at least $25,000 per person and $50,000 per accident for bodily injury. UM/UIM limits generally match your bodily injury liability limits unless you reject higher amounts in writing. The statutory minimum is required; ask about higher limits before rejecting protection above that minimum.
Source details are available through the Kansas Insurance Department consumer auto page and Kansas UM/UIM law. See our Kansas minimum car insurance guide for more detail.
If you’re unsure whether your policy meets Kansas minimums, call 844-712-1313.
Core Coverages for Lenexa Drivers: Liability, Collision, Comprehensive, and PIP
Before removing collision or comprehensive to save money, consider whether you could replace the car and arrange transportation without an insurance payment. Vehicle value, the deductible and coverage cost all matter. Check any financing obligation first, and compare quotes for the alternatives rather than assuming an older car should always have less coverage.
“Full coverage” is informal shorthand. In practice, it typically refers to a policy combining liability coverage, PIP, UM/UIM, collision, and comprehensive coverage. Choose coverage based on your vehicle, finances, driving habits and obligations; compare prices using the same limits and deductibles. Here is what each layer does:
-
Liability coverage: pays for injuries or property damage you cause to others in a covered accident, whether in Lenexa, elsewhere in Johnson County, or anywhere in Kansas. Your own car’s damage is not covered by your liability.
-
Personal Injury Protection (PIP): pays your medical bills and related costs regardless of fault, up to your policy’s limits.
-
Uninsured/Underinsured Motorist: protects you if hit by a driver who carries no insurance or not enough, subject to policy terms and any applicable requirements for hit-and-run claims.
-
Collision coverage: covers damage from accidents with other vehicles, objects, or rollovers. Whether on I-435 or a Lenexa neighborhood street, coverage depends on the loss and your policy terms.
-
Comprehensive coverage: can cover theft, vandalism, fire, hail, falling objects and animal strikes, subject to your policy terms. Ask the insurer whether a particular loss falls within the coverage purchased.
Actual claim outcomes depend on your specific policy language and the insurer’s review of the loss.
How Parked-Car Losses Work in Lenexa
Lenexa households who park at apartment complexes, near Lenexa City Center, or in residential driveways face specific risk categories while their car sits unattended:
-
Hail damage while parked: generally a comprehensive claim. Check your deductible and follow your policy’s claim-reporting requirements.
-
Vandalism (keying, broken windows, slashed tires): generally comprehensive. Document the damage and follow your insurer’s reporting requirements.
-
Theft or attempted theft: generally evaluated under comprehensive coverage if purchased. Liability coverage alone does not pay to replace your stolen car.
-
Hit by another car while parked (hit-and-run): if the other driver is identified, their liability may apply. If the driver is unknown, your collision coverage typically responds after your deductible. Kansas required UM/UIM coverage is for bodily injury, not damage to your car.
No specific outcome is guaranteed. Policy details and the insurer’s claim decision control what is covered and what is paid. Call 844-712-1313 to walk through how your current policy might respond to these scenarios.
Choosing Your Collision and Comprehensive Deductibles
Compare quotes with the same coverage before changing deductibles. Ask about available discounts as a separate step, so you can tell whether a lower price comes from a discount or from accepting more out-of-pocket risk. The Kansas insurance shopper’s guide recommends comparing equivalent coverages and terms.
A deductible is the amount of a covered loss you are responsible for; the insurer generally subtracts it from the claim payment. For a simplified illustration, $3,000 of covered damage minus a $500 deductible leaves $2,500 before any other applicable terms or adjustments. Damage below that deductible ordinarily produces no payment under that coverage.
Ask for quotes at available deductible levels, such as $500 and $1,000. Raising your deductible may reduce the premium, but it increases your share of a covered loss. Compare the actual price difference before deciding.
Factors to weigh when selecting deductibles:
-
Available cash: Could you comfortably absorb a $1,000 share of a covered loss? If not, a lower deductible reduces that immediate burden.
-
Financing or lease requirements: Lenders typically require collision and comprehensive on financed or leased vehicles ; check the specific loan or lease requirements.
-
Vehicle age and value: Compare the vehicle’s value, coverage cost and deductible. Removing optional physical-damage coverage leaves you responsible for losses that coverage might otherwise address.
-
Parking exposure: Consider where you park and which types of damage your chosen coverage addresses.
The NAIC consumer guide explains that higher deductibles lower premiums for otherwise equivalent coverage but increase the amount you must absorb after a loss. An insurance agent at 844-712-1313 can help you compare several deductible combinations.
Do You Need Optional Rental Reimbursement in Lenexa?
Many Lenexa drivers commute to work throughout Johnson County and the Kansas City metro. If your car is in the shop for a week after a covered loss, rental reimbursement may help pay transportation costs within the purchased limits. This is an optional add-on; it is not automatically included with “full coverage.”
How rental reimbursement generally works:
-
Standard rental reimbursement generally follows a qualifying comprehensive or collision loss. It is different from mechanical-breakdown protection; routine maintenance and an ordinary breakdown do not trigger standard accident-related rental reimbursement.
-
Policies set a daily dollar limit and a total claim cap (maximum days or total dollars). If the rental cost exceeds your daily limit, you pay the difference.
When reviewing a policy, consider what transportation you would use while your vehicle is unavailable. The NAIC rental-claim explanation describes purchased rental reimbursement and policy limits. Progressive’s consumer explanation also distinguishes covered losses from mechanical breakdowns and describes daily and total limits; this source is not a statement that the agency represents that insurer. Coverage terms vary by insurer. Call 844-712-1313 to check whether your policy includes this and what limits apply.
Checklist: Setting Up Practical Car Insurance for Your Lenexa Household
Use this list to review your current policy or prepare before requesting quotes:
-
☐ Confirm your policy meets Kansas minimum liability (25/50/25), PIP ($4,500 medical minimum plus other required benefits), and UM/UIM (25/50 bodily injury).
-
☐ Review UM/UIM limits alongside bodily injury limits; discuss the effect of any written rejection of limits above the statutory minimum.
-
☐ Review whether you carry collision and comprehensive, especially if your vehicle is newer or financed.
-
☐ Select deductibles you could realistically pay out-of-pocket after a covered loss.
-
☐ Check whether rental reimbursement is on your policy and whether daily and total limits would cover a rental in Johnson County.
-
☐ Verify all household drivers and vehicles garaged in Lenexa are accurately listed.
-
☐ Compare the final premium for identical limits and deductibles, and ask the insurer to explain any price conditions.
-
☐ Store your insurer’s claims number and Drivers Insurance Agency Inc (844-712-1313) where every driver in your family can find it.
Handling an Accident or Claim in Lenexa
After a crash in Lenexa, there are two separate processes: requesting an accident report from the city and filing a claim with your insurer.
At the scene:
-
Check for injuries and call 911 if needed.
-
Move to a safe location if possible; exchange contact and insurance information with other drivers.
-
Take photos of all vehicles, surroundings, and visible damages.
After the scene:
-
Lenexa Police Department makes accident reports available online roughly seven days after the incident, though timing is not guaranteed. Details are on the Lenexa accident report request page.
-
Contact your insurer or agent separately to start a claim. Insurers typically require notification as soon as possible after the loss. The police report and the insurance claim are independent processes.
Each insurer sets its own claim procedures, and payment or coverage is not guaranteed until the company reviews the loss under your policy terms. If you feel overwhelmed after a crash, call 844-712-1313 for guidance.
Common Questions About Lenexa, KS Car Insurance
Is Kansas minimum car insurance enough if I drive daily in Lenexa?
Kansas minimums (25/50/25 liability, PIP, and UM/UIM) satisfy state law but leave gaps for people who depend on their car every day. Collision, comprehensive, and rental reimbursement can help with eligible vehicle losses or transportation costs, subject to deductibles, limits and exclusions. Compare available quotes using equivalent coverage details. Call 844-712-1313 to review coverage options for your situation.
How does my deductible affect what I pay after a loss?
When a covered claim is approved, the insurer generally subtracts your deductible from the payment. On a $2,000 repair with a $500 deductible, the insurer pays $1,500. Not all situations are covered; actual claim payments depend on policy terms and the insurer’s decision.
Does rental reimbursement pay if my car just breaks down?
Standard accident-related rental reimbursement generally does not cover an ordinary mechanical breakdown or routine maintenance. Separate mechanical-breakdown products can have different benefits. Review your declarations page or call 844-712-1313 to confirm your policy’s terms.
Do I have to visit a specific location to buy coverage?
Call 844-712-1313 to discuss coverage options and receive guidance from a helpful insurance agent without visiting a physical location. Lenexa City Center is a local landmark, not an agency office. A quote is not coverage; confirm the effective date and binding requirements with the insurer or authorized agent.
Talk With a Lenexa-Focused Auto Insurance Agent Today
Review deductible amounts, whether your policy addresses hail, vandalism, and theft through comprehensive, and whether rental reimbursement is in place before you need it. Use your actual driver and vehicle details when requesting a quote.
Contact Drivers Insurance Agency Inc through KansasAutoInsurance.com to discuss available auto insurance options. Call 844-712-1313 today to review your current coverage or request a new quote. A quote is not a binder or policy. Confirm the effective date and binding requirements with the insurer or authorized agent.
Lenexa City Center
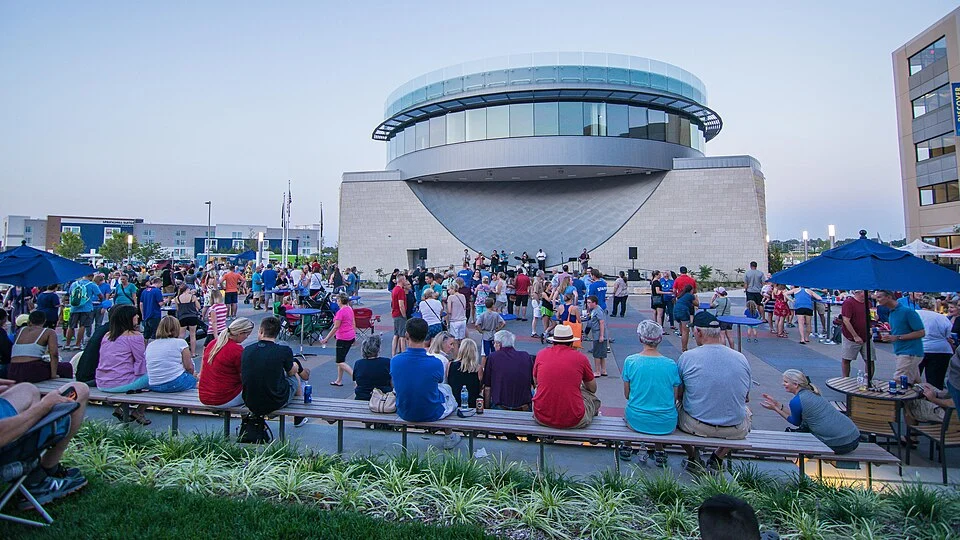

KansasAutoInsurance.com is not affiliated with the City of Lenexa or any government agency. Explore our Kansas city guides.